



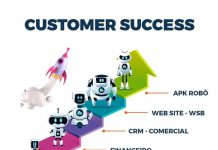
Difícil encontrar um empresário antenado que não entenda quando é preciso mudar para acompanhar a transformação dos tempos. Você não pode ficar para trás! Nós colocamos tecnologia na sua empresa de forma prática e eficiente.
O medo de sair da zona de conforto e agregar novas tecnologias pode custar caro.
Por isso, é importante ficar atento ao timing para adaptar seu negócio ao momento, antes que seja muito tarde. Hoje há muitas possibilidades de inovação, e como diz uma máxima recorrente do meio corporativo, “nenhum modelo negócio está escrito em pedra”.
How Paysafecard Became a Trusted Prepaid Option in Australian Online Gambling
Prepaid payment methods have carved out a distinct space in the Australian online gambling market over the past two decades, and among them, Paysafecard has developed a reputation grounded in practical utility rather than marketing. Its adoption by Australian gamblers reflects broader shifts in how people manage discretionary spending online, particularly in an environment shaped by tightening financial regulations and growing consumer awareness around responsible gambling. Understanding why this particular instrument gained traction requires looking at both the structural features of the product and the specific regulatory and social context of Australia’s gambling landscape.
The Architecture of a PIN-Based Payment System
Paysafecard operates on a debit voucher model that predates the smartphone era. Founded in Vienna in 2000, the company built its business around physical vouchers sold at retail outlets — newsagents, petrol stations, convenience stores — each carrying a 16-digit PIN linked to a fixed monetary value. In Australia, denominations have typically ranged from AUD 10 to AUD 100, with users able to combine up to ten PINs in a single transaction to reach a maximum of AUD 1,000. The transaction itself requires no bank account, no credit card, and no personal financial data transmitted to the merchant. That structural separation between the user’s financial identity and the point of transaction became increasingly valuable as Australian banks began applying pressure on gambling-related payments.
The underlying infrastructure relies on the eCash system, which Paysafecard’s parent company Paysafe Group has refined over years of international deployment. When a user enters a PIN at a gambling site, the value is debited from the voucher in real time. There is no credit facility, no overdraft risk, and no possibility of spending beyond the voucher’s face value. This hard ceiling on expenditure is not incidental — it is the core mechanism that differentiates the product from card-based payments and makes it functionally relevant to harm-minimisation frameworks that Australian regulators have increasingly emphasised.
Regulatory Pressure and the Banking Friction Problem
Australia’s Interactive Gambling Act of 2001 established the foundational legal framework for online gambling, but it was the amendments introduced in 2017 that significantly reshaped the payment environment. The 2017 changes prohibited unlicensed offshore operators from offering services to Australians and placed new obligations on financial institutions to block transactions to those operators. In practice, this created a patchwork outcome: major Australian banks — Commonwealth Bank, Westpac, ANZ, and NAB — began declining or blocking credit card transactions to gambling merchants with increasing frequency, even where those merchants held valid licences in jurisdictions like Malta or Gibraltar that accepted Australian players.
The friction extended to debit cards in some cases, and by the early 2020s, the Australian government had begun consulting on a full credit card ban for online gambling, a measure that eventually took shape in legislative proposals introduced in 2023 and 2024. Against this backdrop, prepaid instruments that bypass the banking network entirely became practically significant for a segment of Australian gamblers who either faced declined transactions or who actively preferred not to have gambling activity appear on bank statements. Paysafecard’s retail distribution network — which by the mid-2010s included thousands of Australian outlets — meant that obtaining a voucher required nothing more than a cash transaction at a local store.
For researchers and consumers tracking the evolution of gambling payment options in Australia, resources such as https://casinozoid.org/paysafecard/ document which licensed platforms currently accept the method and under what conditions, reflecting how the acceptance landscape has shifted as operators adjusted their payment processing arrangements in response to banking restrictions.
Adoption Patterns Among Australian Gambling Platforms
Not all Australian-facing gambling operators integrated Paysafecard at the same pace or for the same reasons. Platforms targeting recreational gamblers with lower average deposit values were among the earlier adopters, recognising that the voucher model aligned naturally with a customer base depositing AUD 20 to AUD 50 at a time rather than making large transfers. The absence of transaction fees for the depositing user — operators absorb processing costs on their end — removed a barrier that had historically made some prepaid instruments less attractive than direct bank transfers for small-value deposits.
The withdrawal limitation is a significant operational reality that shapes how the method is used in practice. Paysafecard does not support withdrawals to vouchers in the standard implementation. Australian operators accepting Paysafecard deposits therefore require players to use an alternative method — bank transfer, e-wallet, or cheque — for cashing out winnings. This asymmetry means that Paysafecard functions as a deposit-only instrument in the gambling context, which has implications for how players structure their accounts. Some operators have introduced Paysafecard’s own digital wallet product, myPaysafecard, which does support two-way transactions, but uptake among Australian gambling platforms has been more limited compared to European markets where the wallet has deeper penetration.
From an operator compliance perspective, Paysafecard deposits present a know-your-customer consideration. Because the vouchers can be purchased with cash and carry no inherent identity linkage, operators must apply their own verification procedures to ensure that the account holder using the PIN has completed identity verification. Australian gambling licences issued by state and territory regulators — including the Northern Territory Racing Commission, which licences the majority of Australia’s online wagering operators — require robust AML and KYC compliance, meaning that the anonymity of the voucher at the point of purchase does not translate into anonymity at the gambling account level.
Responsible Gambling Dimensions and the Prepaid Advantage
One of the more substantive arguments for prepaid gambling payments concerns their structural compatibility with responsible gambling principles. Australia has one of the highest per-capita gambling expenditure rates in the world — estimates from the Australian Gambling Research Centre have placed annual losses at over AUD 1,000 per adult on average, though this figure aggregates across all gambling forms including pokies. Within online gambling specifically, the ability to pre-commit spending is recognised as a harm-reduction tool, and prepaid vouchers operationalise that commitment in a way that relies on behaviour rather than willpower alone.
When a gambler purchases AUD 50 in Paysafecard vouchers and deposits that amount, the physical act of purchasing additional vouchers introduces a friction point that does not exist with a saved card or linked bank account. Research on self-exclusion and deposit limit tools consistently finds that friction — even minor friction — reduces impulsive additional deposits. This is not a complete solution to problem gambling, and Paysafecard itself does not market the product primarily on harm-reduction grounds, but the functional architecture aligns with what behavioural economists describe as commitment devices. The National Consumer Protection Framework for online wagering, which Australian jurisdictions began implementing from 2019 onward, introduced mandatory deposit limits and self-exclusion mechanisms; prepaid instruments can complement these tools by adding an external spending boundary that operates independently of the platform’s own controls.
It is also worth noting that Paysafecard introduced age verification requirements at the retail level in various markets, though the enforceability of these requirements varies by jurisdiction and retailer. In Australia, the broader retail environment for age-restricted products is regulated at the state level, and the practical effectiveness of age checks for voucher purchases remains an area where implementation is inconsistent.
The trajectory of Paysafecard in Australian online gambling illustrates how a payment instrument’s adoption is rarely driven by a single factor. The combination of banking friction created by regulatory changes, the structural spending limits inherent to the voucher model, an established retail distribution network, and the absence of deposit fees for end users created conditions where a product originally designed for European e-commerce found a durable niche in a specific segment of the Australian gambling market. As legislative pressure on credit card gambling payments continues and as banks maintain their cautious approach to gambling transactions, the role of cash-backed prepaid instruments in this market is unlikely to diminish in the near term, even as digital wallet alternatives compete for the same use case.
Por isso, pare e pense. O que diferencia um negócio com alta aderência pelo mercado de outro que não prospera?
👉 Em grande parte, o timing!
E então, como anda o timing da sua imobiliária?
Pronto para atualizar sua estratégia? A Guess está aqui para te ajudar a aumentar em 80% seus resultados!